In mortgage lending, every step of the loan process matters. From application and underwriting to collateral review and closing, delays in one area can affect the entire loan timeline. Property valuation is an important part of this process, and choosing the right appraisal method can make a meaningful difference in how efficiently a loan moves forward.
That brings us to an important question: What is the difference between a desktop appraisal and a traditional appraisal, and how should mortgage lenders decide which option makes sense for a particular loan?
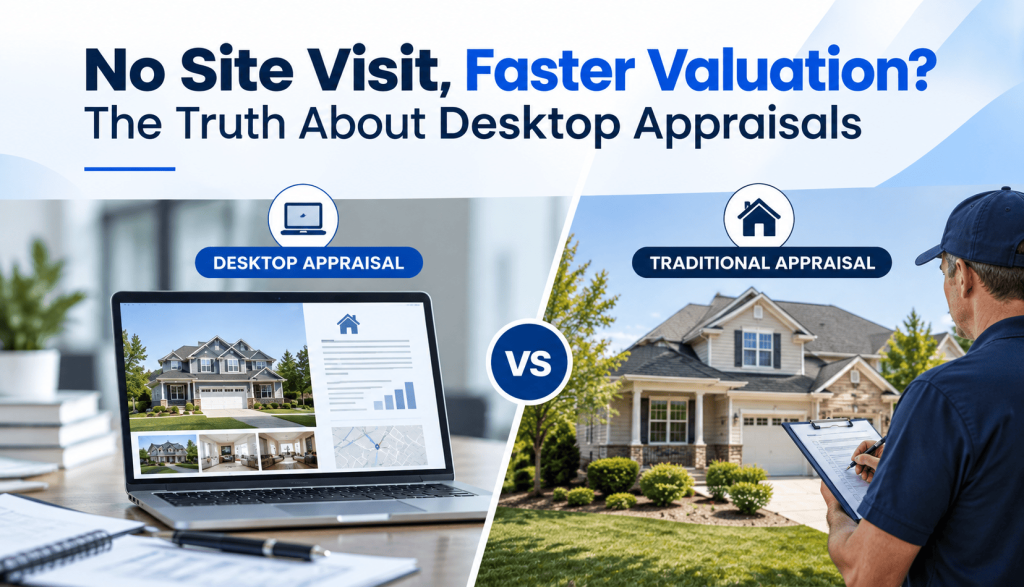
When comparing desktop appraisal vs traditional appraisal, the biggest difference is how the appraiser gathers information about the property. A desktop appraisal relies on available property data and other reliable information without requiring the appraiser to physically inspect the property. A traditional appraisal includes an on-site inspection of the property’s interior and exterior by the appraiser who prepares the report.
Both methods are designed to help establish a credible opinion of market value. However, they differ in inspection requirements, data sources, turnaround considerations, and suitability for different loan scenarios.
For wholesale mortgage lenders, TPO operations teams, underwriters, and collateral-risk professionals, understanding these differences can help improve appraisal ordering decisions, manage operational costs, and maintain appropriate collateral risk controls.
Let’s look at how each method works, where it fits into the lending process, and what lenders should consider before selecting one.
What Is a Desktop Appraisal?
A desktop appraisal is a property valuation completed by a qualified appraiser without a physical on-site inspection of the subject property. Instead of visiting the property, the appraiser analyzes available information to develop an opinion of its market value.
Depending on the assignment, information may come from sources such as:
- Multiple Listing Service (MLS) records
- Public property and tax records
- Property photographs and floor plans
- Previous appraisal reports, where appropriate
- Information from homeowners, real estate agents, or builders
- Other reliable property and market data sources
The appraiser evaluates the available information, researches comparable sales, analyzes relevant market conditions, and determines whether there is enough reliable evidence to support a credible valuation.
However, a desktop appraisal is not simply an automated estimate or a quick review of online property listings. It remains an appraisal assignment that requires professional judgment, appropriate analysis, and compliance with applicable requirements.
For example, under Fannie Mae’s desktop appraisal requirements, eligible assignments use Form 1004 Desktop. The appraiser must assess whether the available data is accurate and reliable enough to support the property’s characteristics, condition, and value. The required report also includes a floor plan.
What Is a Traditional Appraisal?
A traditional appraisal is a property valuation in which the appraiser personally visits the subject property and visually inspects its interior and exterior as required by the assignment.
During the inspection, the appraiser gathers information about the property’s characteristics and condition. This may include:
- Property size, layout, and room configuration
- Overall condition and quality of construction
- Interior and exterior features
- Renovations, upgrades, or visible deferred maintenance
- Site characteristics and relevant external influences
- Features that may affect the property’s marketability or value
After the inspection, the appraiser researches comparable properties, analyzes recent sales and market conditions, makes appropriate adjustments, and develops an opinion of market value.
For instance, two homes in the same neighborhood may have similar square footage and bedroom counts but very different interior conditions. One may have a recently renovated kitchen and updated bathrooms, while the other may require substantial repairs. An on-site inspection can provide direct observations that help the appraiser understand these differences.
Desktop Appraisal vs Traditional Appraisal: Key Differences
Although both appraisal methods aim to establish a credible opinion of market value, their processes are different. Here is a side-by-side comparison to help lenders understand what sets them apart.
| Comparison Factor | Desktop Appraisal | Traditional Appraisal |
|---|---|---|
| Physical inspection | No on-site inspection by the appraiser | Appraiser personally inspects the property |
| Property information | Available records, images, floor plans, and other reliable sources | Available data plus direct inspection observations |
| Property condition | Assessed using sufficiently reliable available information | Observed directly during the inspection |
| Workflow | Removes the appraiser’s travel and site visit | Requires scheduling and completing the inspection |
| Turnaround | May reduce scheduling-related delays | Can depend on property access and appraiser availability |
| Eligibility | Must meet applicable program requirements | Used when appropriate to the assignment and requirements |
| Quality control | Focuses on data reliability and valuation analysis | Includes inspection findings and valuation analysis |
One important point: a desktop appraisal is not automatically faster in every situation, and a traditional appraisal is not automatically more accurate in every situation. Turnaround and reliability depend on the assignment, data quality, appraiser expertise, market conditions, and applicable lending requirements.
The right approach is to match the appraisal method to the property’s characteristics, the transaction’s eligibility, and the lender’s risk-management requirements.
How Does a Desktop Appraisal Work?
Understanding the workflow helps lenders determine whether a desktop appraisal is a practical option for a particular transaction.
1. The Lender Confirms Eligibility
Before ordering a desktop appraisal, the lender checks the transaction against applicable investor and program requirements. Eligibility depends on factors such as property type, occupancy, loan purpose, loan characteristics, and automated underwriting findings.
Fannie Mae’s Desktop Underwriter (DU) may identify eligible loan casefiles for the desktop appraisal option. Eligibility depends on the specific transaction and its characteristics. Lenders should consult current guidelines rather than assume a desktop appraisal is acceptable for every loan.
2. The Appraiser Gathers Property Information
The appraiser collects relevant information from available sources, including property records, photographs, floor plans, MLS data, and other reliable documentation.
Information supplied by a homeowner, real estate agent, or another party with a financial interest in the transaction must be verified through a disinterested source when required by the applicable guidelines.
3. The Appraiser Analyzes Comparable Sales
Comparable sales, commonly called comps, help the appraiser understand how similar properties have performed in the market.
The appraiser considers factors such as location, property size, condition, features, and sale dates. Differences between the subject property and comparable properties may require adjustments to support the valuation analysis.
4. The Appraiser Completes the Report
Once the appraiser has evaluated the available evidence, they prepare the report using the required form and reporting standards. For assignments under Fannie Mae’s desktop appraisal requirements, Form 1004 Desktop is used, and a floor plan is required.
5. The Lender Reviews the Appraisal
The lender reviews the completed report to ensure it meets the applicable requirements and that the property information and valuation analysis are adequately supported. Missing information, inconsistencies, or unresolved concerns may require additional documentation or corrective action before the loan can proceed.
How Does a Traditional Appraisal Work?
A traditional appraisal follows a similar valuation process, but it includes a physical inspection by the appraiser.
1. The Appraisal Is Ordered
The lender or its appraisal management partner places the order with an appropriately qualified appraiser based on the assignment requirements and applicable independence rules.
2. The Inspection Is Scheduled
The appraiser coordinates access to the property with the appropriate parties. Scheduling can depend on the borrower’s availability, property access, geographic coverage, and the appraiser’s workload.
3. The Appraiser Inspects the Property
During the site visit, the appraiser visually examines the interior and exterior as required by the assignment. The appraiser records relevant characteristics and observations about the property’s condition, layout, quality, and features.
4. The Appraiser Researches the Market
Following the inspection, the appraiser analyzes comparable sales, current market conditions, and other relevant valuation evidence. The physical inspection provides direct observations, but the valuation must still be supported by credible market data and appropriate analysis.
5. The Report Is Completed and Reviewed
The appraiser prepares the report, and the lender reviews it for completeness, consistency, and compliance with applicable requirements. If revisions or clarification are needed, additional communication may be required before the loan can move forward.
What Are the Benefits of a Desktop Appraisal?
For mortgage lenders managing high loan volumes, desktop appraisals can offer several operational advantages when the transaction qualifies and reliable information is available.
Potentially Shorter Turnaround Times
Removing the appraiser’s physical site visit eliminates one step from the process. When property information is readily available, this may help reduce scheduling delays and support a more efficient valuation workflow. Overall turnaround still depends on data availability, assignment complexity, appraiser capacity, and review requirements.
Greater Flexibility in Appraisal Operations
Desktop appraisals can help lenders manage certain eligible assignments without coordinating an on-site visit. This can be useful when physical access or scheduling is challenging, provided the selected appraisal method is permitted and the necessary information can be verified.
More Efficient Use of Appraisal Resources
By eliminating the site visit for eligible assignments, desktop appraisals can reduce travel and scheduling demands. This may help appraisal professionals allocate their time across different assignments.
Support for Digital Lending Workflows
Desktop appraisals rely on digital information, electronic documentation, and data analysis. When integrated into a lender’s existing processes, they can support a more technology-enabled approach to collateral valuation.
Potential Operational Cost Savings
Removing a physical inspection may reduce certain process related expenses. However, actual appraisal fees and total loan production costs vary by assignment, market, provider, and the level of analysis required. Lenders should evaluate the overall cost rather than assume every desktop appraisal will be less expensive.
What Are the Benefits of a Traditional Appraisal?
Traditional appraisals remain important because some transactions require direct property inspection, and some properties are difficult to evaluate reliably using available data alone.
Direct Observation of Property Condition
An on-site inspection allows the appraiser to observe the property’s interior and exterior firsthand. This can be particularly valuable when condition, workmanship, renovations, or visible maintenance issues may affect the valuation.
Better Understanding of Unusual Property Characteristics
A property with a unique layout, substantial additions, unusual features, or limited comparable sales may require additional investigation. A physical inspection can provide context that is difficult to establish from photographs or public records alone.
Additional Evidence for Collateral Risk Assessment
For underwriting and collateral risk teams, direct inspection observations can provide useful evidence about the subject property’s characteristics. However, incorrect records, weak comparable sales, unsupported adjustments, or incomplete reporting can affect any appraisal method. Quality review remains essential.
Suitability for Transactions That Require an Inspection
When investor guidelines, loan program requirements, or the specific assignment require an on-site inspection, a desktop appraisal cannot simply replace the traditional appraisal. The required scope of work must be followed.
What Are the Limitations of a Desktop Appraisal?
Desktop appraisals can improve workflow efficiency, but lenders should understand their limitations before incorporating them into their appraisal strategies. The main consideration is the availability and reliability of property information.
Suppose a property record indicates that a home has three bedrooms and two bathrooms. However, the home has undergone an unrecorded renovation, or the available photographs do not accurately reflect its current condition. If reliable information cannot be obtained and verified, the appraiser may not have sufficient evidence to develop a credible valuation.
- Incomplete property data: Missing floor plans, outdated photographs, or conflicting records may require additional research.
- Limited visibility into current condition: Without a physical inspection, the appraiser does not personally observe the property’s interior and exterior.
- Complex property characteristics: Unique homes or properties with unusual features may require a different scope of work.
- Eligibility restrictions: A desktop appraisal is not permitted for every loan or property type.
- Continued lender accountability: Selecting an alternative valuation method does not remove the lender’s responsibility to follow applicable requirements and manage collateral risk.
The practical lesson: a desktop appraisal works best when the assignment qualifies and the available evidence is sufficient to support a reliable valuation.
When Should Lenders Choose a Desktop Appraisal vs Traditional Appraisal?
The decision should begin with eligibility, followed by an assessment of data reliability and collateral risk.
A desktop appraisal may be appropriate when the transaction meets the relevant program requirements, the property information is sufficiently complete, and the appraiser can develop a credible opinion of value without a site visit.
A traditional appraisal may be necessary when the transaction requires a physical inspection or when the property’s characteristics and available information make direct observation important to the assignment.
Scenario 1: An Eligible Purchase Transaction With Reliable Property Data
A lender receives an eligible purchase loan with readily available property records, photographs, and sufficient market information. If the applicable program permits a desktop appraisal and the appraiser can verify the necessary information, the desktop option may support an efficient valuation process.
Scenario 2: A Property With Unclear Condition Information
The available records describe a home as being in good condition, but the photographs are outdated and there is conflicting information about recent renovations. The lender should not assume that a desktop appraisal is sufficient simply because it may be quicker. The assignment must be evaluated against applicable requirements and the appraiser’s ability to establish a credible valuation.
Scenario 3: A Transaction That Does Not Meet Desktop Eligibility Requirements
A loan involves a property type or transaction that falls outside the applicable desktop appraisal eligibility criteria. In that case, the lender must select an eligible valuation option that satisfies the relevant requirements.
Desktop Appraisal vs Traditional Appraisal: What Should Lenders Consider?
For TPO lenders, the decision involves more than the difference between a property visit and a digital review. It also affects appraisal ordering, loan manufacturing, pipeline management, and quality control.
1. Confirm Eligibility Before Placing the Order
Establish a clear process for checking investor requirements and automated underwriting findings before selecting the appraisal type. This reduces the risk of ordering a valuation that does not meet the transaction’s requirements and then needing to reorder the appraisal or delay the file.
2. Evaluate the Quality of the Available Data
A desktop appraisal depends on reliable information. Lenders should pay attention to missing documentation, inconsistencies between sources, and property characteristics that cannot be adequately verified. Better data management helps support more informed appraisal decisions.
3. Monitor the Entire Appraisal Timeline
The time required to complete an appraisal is only one part of the process. Lenders should also monitor order acceptance, information requests, report delivery, quality review, revision requests, and final resolution. These steps help operations teams identify where appraisal delays occur and where workflow improvements may be possible.
4. Maintain Consistent Quality-Control Standards
A faster process does not automatically produce a better lending outcome. Every appraisal should be evaluated against the applicable requirements for completeness, supporting evidence, and credible valuation analysis. If an appraisal raises concerns, the lender should follow the appropriate review and resolution procedures rather than prioritizing speed alone.
5. Work With an Appraisal Management Partner That Provides Visibility
An effective appraisal management process can help lenders coordinate orders, communicate with appraisers, track status, and identify issues that need attention. For lenders managing multiple channels and changing loan volumes, clear communication and consistent quality review can help reduce administrative friction.
How Does an Appraisal Management Company Help?
An appraisal management company (AMC) can support lenders by coordinating appraisal assignments, managing communication, tracking order progress, and helping maintain appropriate quality and compliance processes. The specific responsibilities depend on the lender’s agreement with the AMC and the services provided.
When comparing desktop appraisal vs traditional appraisal workflows, a capable AMC can help the lender understand the requirements of the selected assignment, coordinate the appropriate appraiser, monitor progress, and address report issues through the proper channels.
For example, a lender’s operations team may have several appraisal orders waiting for updates. Without clear order visibility, employees may need to contact multiple parties individually to determine which reports are delayed, which need additional information, and which are ready for review.
A structured appraisal management workflow can make these statuses easier to track and help teams focus on orders that require action. For lenders, the value lies in having a more organized process, not simply in selecting the appraisal method with the fewest steps.
How Signature AMC Supports Appraisal Management?
Signature AMC supports mortgage lenders and brokers with appraisal management services designed around quality, compliance, communication, and workflow visibility.
For lenders evaluating different appraisal options, an organized appraisal management process helps keep assignment requirements, appraiser coordination, order status, and report review in focus.
Signature AMC highlights several capabilities relevant to this process:
- Qualified appraiser network: A private appraisal panel that can be built around client criteria and preferences.
- Built-in quality control: An additional review of reports before delivery.
- Order visibility: A centralized interface for managing appraisal orders and monitoring progress.
- Client and vendor software: A shared platform designed to reduce the need to navigate separate portals.
- Seven day support: Access to assistance by phone or email throughout the week.
These capabilities can help lenders manage appraisal workflows more consistently while keeping communication and quality review central to the process.
The right appraisal method will still depend on the individual transaction, the applicable investor requirements, and the reliability of the available property information. An appraisal management partner helps support that process; it does not replace the lender’s underwriting responsibilities or the appraiser’s independent professional judgment.
Looking for a More Organized Appraisal Workflow?
Signature AMC helps lenders manage valuation assignments with qualified appraisers, quality-control review, order visibility, and responsive support.
Final Thoughts
When comparing desktop appraisal vs traditional appraisal, the goal should not be to choose the fastest option in every situation. It should be to choose the valuation method that fits the transaction, meets the applicable requirements, and provides sufficient evidence to support a credible opinion of market value.
Desktop appraisals can help eligible lenders streamline certain valuation workflows by removing the appraiser’s physical inspection step. Traditional appraisals remain essential when an on-site inspection is required or when direct observation is important to the assignment.
For wholesale mortgage lenders, underwriting teams, and collateral-risk professionals, a thoughtful appraisal strategy combines eligibility checks, reliable data, appropriate quality controls, and clear order visibility.
With the right process and appraisal management support, lenders can make informed valuation decisions while keeping loan quality, operational efficiency, and collateral risk in balance.
Learn more: Visit Signature AMC to explore appraisal management and valuation services.
Frequently Asked Questions: Desktop Appraisal vs Traditional Appraisal
1. What is the difference between a desktop appraisal vs traditional appraisal?
A desktop appraisal is completed remotely using property data, comparable sales, public records, and other available information without the appraiser physically visiting the property. A traditional appraisal generally includes an on-site property inspection. Both approaches help estimate market value, but the appropriate method depends on the property, loan requirements, available data, and applicable appraisal standards.
2. Is a desktop appraisal as accurate as a traditional appraisal?
A desktop appraisal can provide a reliable value estimate when accurate property information, relevant comparable sales, and sufficient market data are available. However, without an on-site inspection, the appraiser may have limited information about the property’s interior condition or unreported improvements. The reliability of either approach depends on the quality of the data, the appraiser’s analysis, and the complexity of the property.
3. Is a desktop appraisal faster than a traditional appraisal?
A desktop appraisal can often be completed faster because it does not require scheduling an on-site inspection or coordinating property access. Turnaround time still depends on data availability, property complexity, appraiser workload, and review requirements. For mortgage lenders, desktop appraisals may help reduce appraisal delays when the loan is eligible for this valuation method.
4. Is a desktop appraisal cheaper than a traditional appraisal?
Desktop appraisals may cost less because they eliminate the need for an appraiser to travel to and inspect the property. However, actual pricing varies by provider, property type, market, and assignment requirements. Lenders should compare the total cost, expected turnaround time, and suitability of the valuation method rather than choosing based on price alone.
5. When should a lender choose a desktop appraisal over a traditional appraisal?
A lender may consider a desktop appraisal when the loan program permits it, reliable property data is available, and the property can be evaluated adequately without an on site inspection. A traditional appraisal may be more appropriate when the property is unusual, its condition is uncertain, comparable sales are limited, or the lender or investor requires an inspection based valuation. Eligibility should always be confirmed against current loan program and investor guidelines.
6. Does a desktop appraisal require a property inspection?
A desktop appraisal generally does not require the appraiser to physically visit the property. Instead, the appraiser uses available records, property characteristics, comparable sales, and other reliable data sources. The assignment must meet the applicable appraisal standards and lender requirements, and additional information or an inspection may be needed if the available data is insufficient.
7. What is the difference between a desktop appraisal and a hybrid appraisal?
A desktop appraisal is generally completed remotely using available property information without an on-site inspection by the appraiser. A hybrid appraisal typically combines an inspection performed by a separate qualified property data collector with the appraiser’s analysis and valuation. The exact inspection scope, data collection process, and eligibility requirements depend on the applicable assignment and lending guidelines.
8. How can an appraisal management company help with desktop and traditional appraisals?
An appraisal management company (AMC) can help coordinate appraisal orders, assign qualified appraisers, monitor turnaround times, manage communications, and support quality control processes. For both desktop and traditional appraisals, effective appraisal management can help lenders maintain consistent workflows, address missing information, and reduce avoidable delays. The specific services provided depend on the AMC and the lender’s requirements.